Important
This platform provides analytical frameworks for informational purposes only
Nothing on this site constitutes financial advice or a recommendation to trade
Rigorous. Practitioner-led. Real.
I built this because the gap in drawdown thinking was costing portfolios dearly
I spent years watching capable allocators get blindsided by multi-period drawdown
cascades — not because they lacked intelligence, but because the frameworks simply did
not exist in one place. This platform is the answer I wished I had earlier.
Practitioner-designed analytical frameworks
Multi-horizon drawdown control focus
Transparent, evidence-based methodology
Institutional-grade risk perspectives
Finding your footing when markets turn against you
I used to think a single-period view of drawdown was enough — until a sequence of correlated corrections showed me exactly how wrong that assumption was. This platform exists to close that gap, one rigorous framework at a time.
1Planning & Advice
A structured lens for multi-period allocation decisions
Before I built this, I watched allocators rely on single-snapshot drawdown metrics and get burned repeatedly across consecutive periods. The platform provides a structured analytical lens that maps drawdown exposure across multiple horizons simultaneously, so decisions are made with full sequence-of-returns awareness rather than a narrow point-in-time view.
View methodology
2Unified Account View
All risk exposures visible in one connected framework
Fragmented views across accounts are where drawdown risk hides. The platform's unified analytical framework pulls every allocation layer into a single coherent picture, revealing correlated exposures that siloed reviews consistently miss. Think of it as switching from individual weather station readings to a full synoptic chart — the storm becomes obvious before it arrives.
See how it works
3Everyday Guidance
Drawdown awareness built into daily allocation thinking
Risk discipline is not a quarterly exercise — it is a daily habit. The platform embeds
drawdown control checkpoints into the routine analytical workflow, making it natural to
ask the right questions before each allocation adjustment rather than scrambling after a
correction has already begun. It is the difference between carrying an umbrella and
chasing one.
Explore resources
4Analytical Tools
Dynamic allocation tools that respond to shifting conditions
Static allocation rules crumble when volatility regimes shift. The platform's
analytical tools are built around dynamic adjustment logic — responsive frameworks that
recalibrate drawdown thresholds as market conditions evolve across periods. The result
is an approach that holds its shape under pressure, rather than one that looks elegant
only in a calm environment.
Read the curriculum
The principles that keep this platform honest with itself
I have seen enough polished-but-hollow financial content to know that values without friction are just marketing. Every principle below has been tested against a real decision where following it was the harder choice — and we chose it anyway. These are not aspirations. They are operating constraints.
Intellectual Rigour Above Comfort
I made a decision early on: if a framework cannot survive scrutiny from a sceptical quantitative analyst, it does not belong in the curriculum. That means we retire ideas when evidence contradicts them, we flag the limits of every model we present, and we never dress up a heuristic as a theorem. Rigour is not a style choice here — it is the only way I know how to sleep at night.
Practitioner Relevance, Always
Academic elegance that dissolves under real allocation pressure is worse than useless — it gives false confidence. Every framework on this platform has been stress-tested against actual multi-period drawdown scenarios, not just backtested on clean historical data. If something works in theory but collapses in practice, I say so plainly and show the failure mode in detail.
Continuous Improvement, Not Nostalgia
The platform I launched is not the platform running today, and the one running today will not be the one running next year. Volatility regimes change, correlation structures shift, and analytical best practices evolve. I treat the curriculum as a living document — reviewed regularly against current market behaviour and updated when the evidence demands it, not on a comfortable annual schedule.
Transparency in Risk Communication
Drawdown risk is genuinely uncomfortable to communicate clearly, so most platforms obscure it behind optimistic framing. I do the opposite. Every tool and framework on this platform comes with an explicit discussion of its assumptions, its edge cases, and the conditions under which it is likely to underperform. Transparency is not a legal box to tick — it is the foundation of any useful risk dialogue.
Commitment to Participant Outcomes
A participant who finishes a module but cannot apply the framework to a real allocation decision has not actually benefited — and I take that personally. The curriculum is designed around application, not comprehension alone. Every analytical method is paired with a worked scenario, and every scenario is chosen because it represents the kind of situation practitioners actually face, not the kind that makes the method look best.
The practitioners who built and run this platform's analytical core
I did not want a team of generalists who had read about drawdown control — I wanted people
who had managed real allocation decisions under real drawdown pressure. Every lead
instructor and curriculum designer on this platform comes from an institutional background,
with hands-on experience in multi-period risk management and quantitative research. Their
track records speak through the quality of the frameworks, not through polished bios.
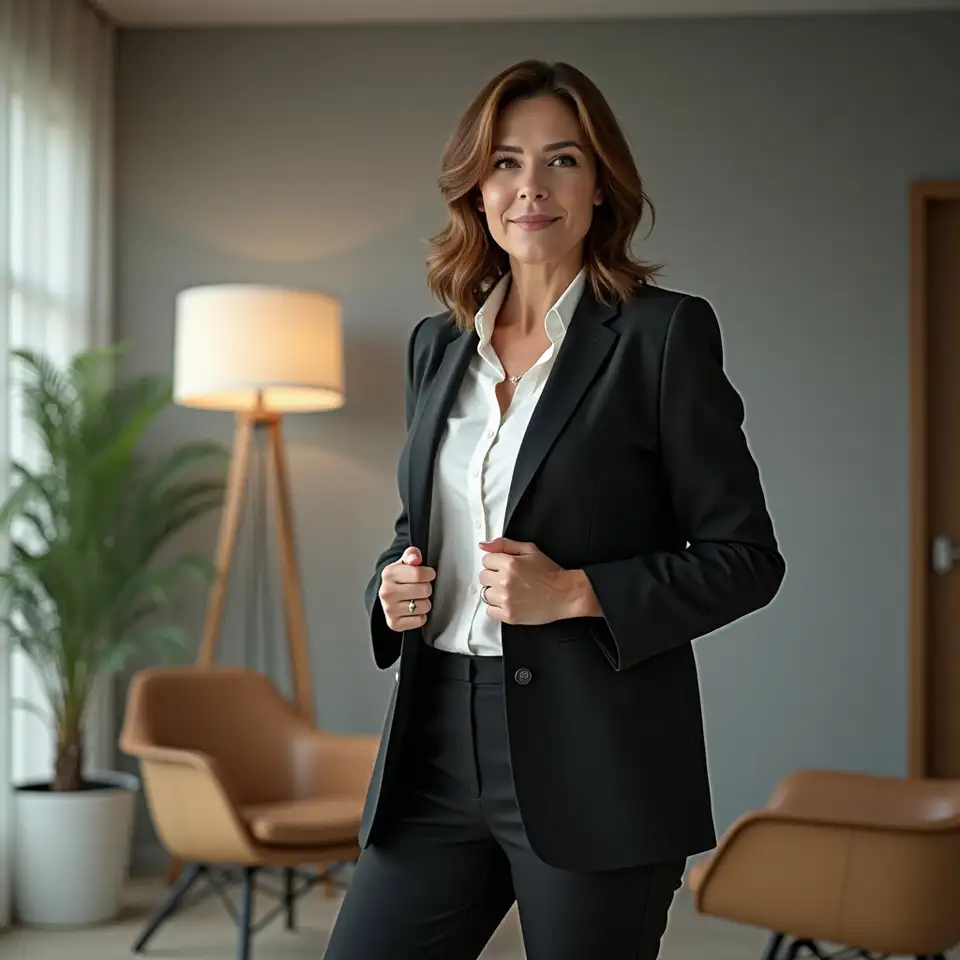
Dr. Eleanor Marsh, CFA, FRM
Lead Curriculum Designer and Senior Risk Analyst
Based in Sydney, New South Wales, Australia
Eleanor spent over a decade as a risk officer at an institutional asset allocator before joining this platform. She built the foundational drawdown control curriculum from scratch, drawing on case studies from real allocation cycles where single-period thinking failed. Her approach is methodical, direct, and refreshingly free of jargon.
Core areas of analytical focus
Multi-period drawdown modelling
Dynamic allocation adjustment frameworks
Tail risk scenario construction
Quantitative volatility regime analysis
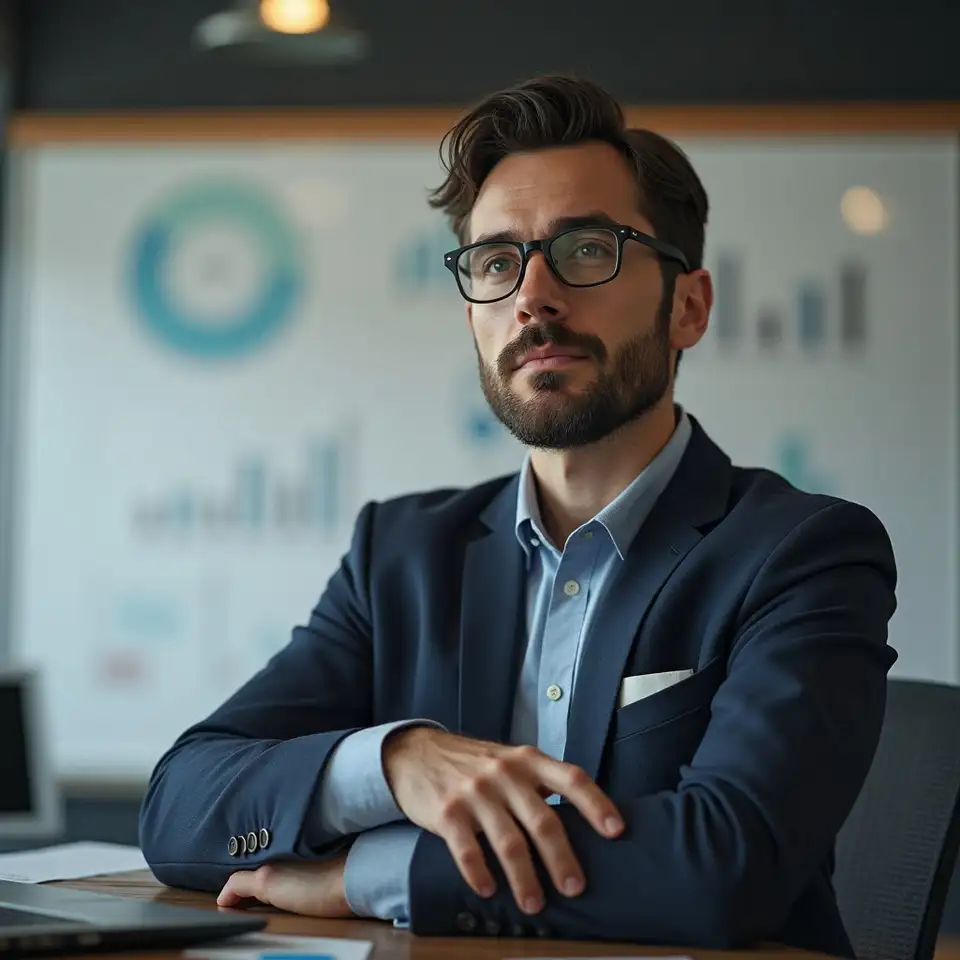
Marcus Thiele, PhD, CAIA
Quantitative Research Lead and Framework Architect
Based in Melbourne, Victoria, Australia
Marcus came to this platform after years building quantitative models for a multi-strategy institutional fund. He is the architect behind the platform's dynamic adjustment logic — the engine that allows drawdown thresholds to respond to shifting volatility regimes rather than sitting frozen at inception. He writes every technical specification himself.
Stochastic drawdown path simulation
Correlation structure breakdown analysis
+2
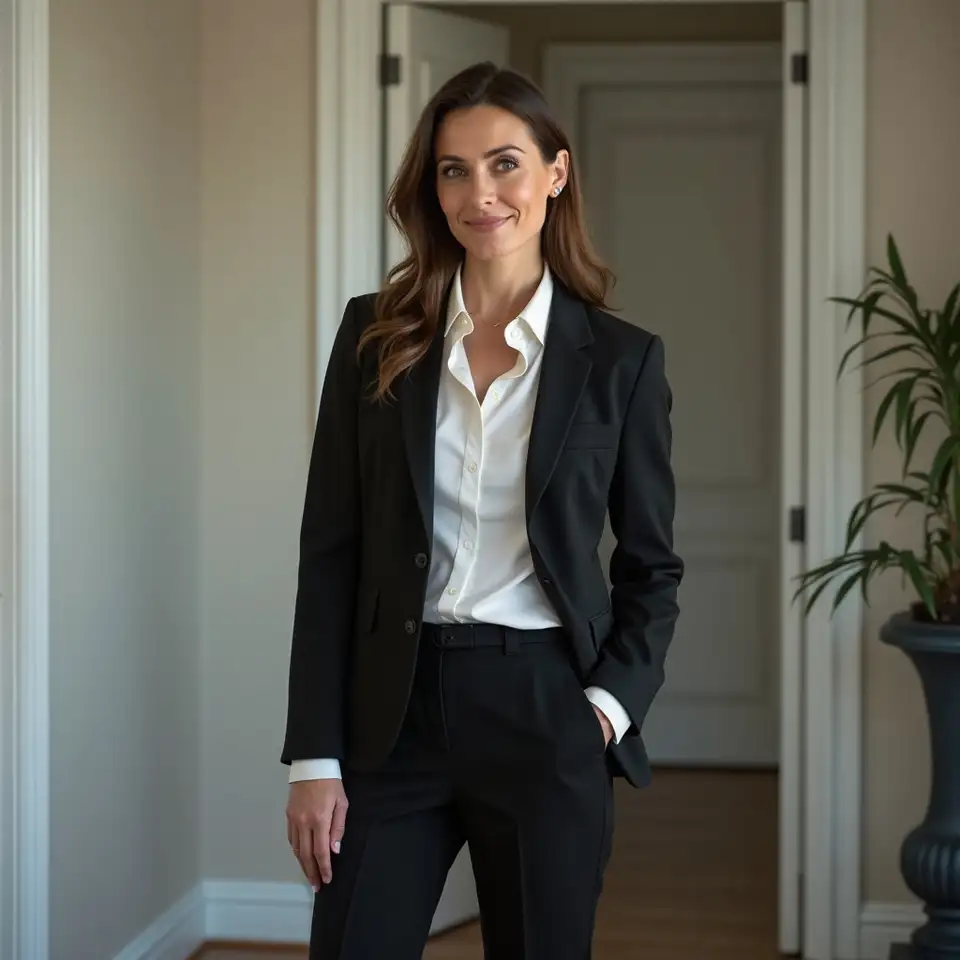
Priya Nair, MSc Finance, CFA
Instructor and Applied Scenarios Specialist
Based in Brisbane, Queensland, Australia
Priya's background is in applied portfolio risk review at a large superannuation fund, where she led the team responsible for communicating drawdown exposure to non-technical stakeholders. She translates complex multi-period frameworks into clear, applicable analytical steps — the kind you can actually use the morning after completing a module.
Worked drawdown case study development
Multi-horizon allocation review processes
+2
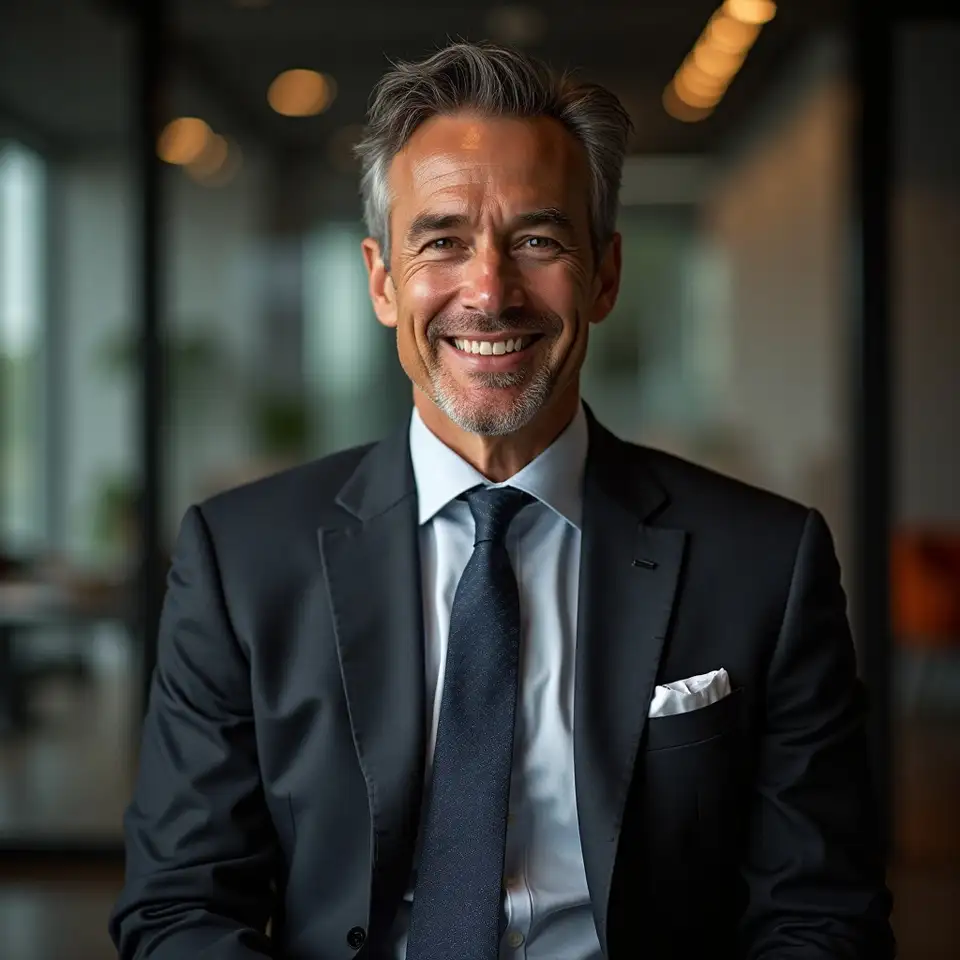
James Kowalski, MBA, FRM
Operations Director and Curriculum Integration Lead
Based in Perth, Western Australia, Australia
James oversees how the platform's analytical frameworks connect with each other across the full curriculum arc. Before joining, he spent years translating institutional risk management processes into formats that practitioners at varying experience levels could genuinely absorb. He is the reason the platform feels like a coherent system rather than a collection of separate modules.
Curriculum sequencing and coherence review
Institutional risk framework translation
+2
Recognised Authority
Excellence in Risk Curriculum
RMAA
2024Best Analytical Framework
FinEdge
2023Academic Partnership Award
APRA Forum
2022Media Recognition in Risk Analysis
InvestorWeekly
2023Practitioner Resource Commendation
QuantConnect
2024How this platform came to exist and where it stands today
Every milestone below represents a decision to go deeper rather than broader — to build something genuinely useful for practitioners managing real drawdown exposure across multiple periods.
2018
The gap identified — platform concept formed
After witnessing a sequence of correlated drawdowns expose the limits of single-period allocation thinking, the founding team began mapping out a systematic framework for multi-period drawdown control. The concept was simple: practitioners deserved rigorous, applied tools, not simplified heuristics dressed up as models.
2018
2019
First analytical cohort launched in Sydney
The inaugural cohort brought together a group of institutional allocators and risk analysts for the platform's first structured review of multi-period drawdown frameworks. Feedback from that cohort directly shaped the curriculum structure that underpins the platform today. It was a genuine dialogue, not a lecture series.
2019
2020
Volatility stress-testing module introduced
In response to the market volatility of early 2020, the platform accelerated development of a dedicated volatility regime stress-testing module. The module examined how dynamic allocation adjustments behaved across rapid drawdown sequences — a real-world test case that validated several core framework assumptions and challenged others.
2020
2021
Quantitative research publication and peer review
The platform published its first formal research paper on dynamic drawdown threshold recalibration, submitted for peer review through an Australian finance research network. The paper was cited in subsequent practitioner discussions and helped establish the platform's credibility as an analytically serious resource rather than a commercial product.
2021
2023
Institutional partnership programme expanded
Formal analytical partnerships with a growing number of institutional allocators allowed the platform to stress-test its frameworks against live allocation environments. These partnerships are not endorsements — they are working relationships that generate real feedback and keep the curriculum calibrated to current market conditions.
2023
2025
Curriculum fully updated for current volatility regimes
A comprehensive curriculum review updated every core module to reflect current correlation structures, volatility regime behaviour, and dynamic allocation adjustment research. The review was conducted by the full practitioner team and resulted in material changes to three foundational frameworks — changes we communicated openly to all participants.
2025